What Liability Coverage Pays for on a Resource Road
Heading out on the winding, gravel paths of British Columbia's resource roads with your ATV or UTV offers an unparalleled sense of freedom and adventure. Yet, many riders find themselves scratching their heads when it comes to insurance—specifically, what liability coverage actually does for them when they're far from paved roads. This guide aims to clear up that confusion, explaining precisely what liability coverage pays for on these unique and often demanding routes.
Understanding the Unique Landscape of BC Resource Roads
British Columbia is a vast province, and much of its accessible backcountry is crisscrossed with what we commonly call "resource roads." These aren't your typical highways or even rural paved roads. They are the working arteries of industries like forestry and mining, and they come with their own set of rules, risks, and, yes, insurance requirements.
What Exactly Is a Resource Road?
When we talk about resource roads, we're primarily referring to Forest Service Roads (FSRs) or other industrial roads. These roads are often unpaved, sometimes narrow, and can be quite rugged. They were built and are maintained for industrial purposes—think logging trucks, heavy machinery, and industrial crews—but many are also open to the public for recreational use. From the sweeping vistas of the Kootenays to the dense forests of Vancouver Island, these roads unlock incredible access to nature. However, their primary function means they can be incredibly busy with commercial traffic, especially on weekdays. It's not uncommon to encounter a fully loaded logging truck barreling down the road, and these vehicles always have the right of way. Understanding [BC Rules for Riding a Forest Service Road] is crucial for your safety and legal compliance.
Why Resource Roads Are Different from Highways
Legally speaking, resource roads are distinct from highways. While both are public thoroughfares, the Off-Road Vehicle Act governs ATVs and UTVs on resource roads and other Crown land, whereas the Motor Vehicle Act governs highway use. This distinction is vital for insurance purposes. On a paved highway, your machine would need to be registered under the Motor Vehicle Act and carry full Basic Autoplan insurance, which is almost impossible for most ATVs and UTVs as they aren't "street legal" in BC. On a resource road, the rules are specific to off-road vehicles. These roads often lack clear signage, have variable surface conditions, and present unique hazards like washouts, active hauling, and remote locations with no cell service. The sheer remoteness can turn a minor incident into a significant emergency, making robust liability coverage even more critical.
The Basics of ATV/UTV Insurance in BC
Just like with your road vehicle, insurance for your ATV or UTV in British Columbia isn't a one-size-fits-all situation. There's a blend of mandatory requirements, particularly for certain types of Crown land, and optional coverages that can offer much greater peace of mind. It’s important to remember that [BC Insurance Bought With Registration] is a separate consideration from any additional private policy you might choose.
The Public Insurer: ICBC's Role with ORVs
In British Columbia, ICBC (the Insurance Corporation of British Columbia) is the sole provider of mandatory basic auto insurance for vehicles registered under the Motor Vehicle Act. For off-road vehicles, however, their role is a bit different. When you register your ATV or UTV under the Off-Road Vehicle Act, you obtain a Certificate of Registration and a number plate. This registration process is mandatory if you plan to ride on Crown land, which includes most resource roads. While this registration ensures your machine is legally identifiable, it doesn't automatically come with comprehensive insurance coverage beyond a very specific, basic liability that applies only to Forest Service Roads. This mandatory coverage is the bare minimum, offering a specific amount of third-party liability that we'll dive into shortly. For many riders, especially those who've invested in quality accessories like heavy-duty winches or skid plates from SuperATV, relying solely on this basic coverage feels insufficient.
Private Insurance Options for Off-Road Adventures
Given the limited scope of ICBC's mandatory ORV liability, many riders wisely turn to private insurance companies. These insurers offer a range of policies specifically designed for ATVs, UTVs, dirt bikes, and snowmobiles. These private policies can provide much broader coverage, including collision, comprehensive, and significantly higher third-party liability limits. Think about it: if you accidentally damage an expensive piece of logging equipment or cause a serious injury to another rider, the basic $200,000 liability might not even scratch the surface of the costs. Private insurance allows you to customize your coverage, often offering options for theft, fire, vandalism, and even coverage for aftermarket parts you’ve added, which is a huge benefit if you've kitted out your machine with accessories that enhance performance or safety. These options bridge the [BC Insurance Price Gaps Riders Talk About], providing a more complete safety net.
Mandatory vs. Voluntary Coverage on Resource Roads
This is where things can get a little tricky, and it's perhaps the most common area of confusion for riders hitting BC's backcountry. Not all Crown land is treated equally when it comes to insurance, and understanding the nuances is critical to staying legal and protected. Remember, [BC Crown Land Triggers the Registration Rule] for your machine, but the specific type of Crown land dictates your insurance obligations.
The $200,000 Requirement on Forest Service Roads
If you plan to ride on a Forest Service Road (FSR), there is a mandatory insurance requirement that states you must carry a minimum of $200,000 in third-party liability coverage. This specific amount is part of the Off-Road Vehicle Regulation. Where does this come from? It's generally provided by ICBC when you register your ORV and declare that you'll be using it on FSRs. This coverage is intended to protect you if you are found at fault for causing property damage or bodily injury to another person while operating your ORV on an FSR. This could mean anything from hitting another vehicle, damaging a culvert, or even causing an injury to a passenger in another vehicle. It's a critical safety net given the active industrial traffic on these roads. Think of it as the province's way of ensuring that serious accidents don't leave victims entirely without recourse.
Voluntary Coverage for Other Crown Land Riding
Now, here's where the distinction becomes crucial. While $200,000 in liability is mandatory for FSRs, for all other types of Crown land—such as provincial parks (where ORV use is permitted, which is rare in many), vast tracts of unsurveyed wilderness, or general Crown land trails not designated as FSRs—third-party liability insurance is voluntary. This means that while you still need to register your machine with ICBC to ride on this Crown land, you are not legally required to carry the $200,000 liability. However, "voluntary" doesn't mean "unnecessary." Quite the opposite. Riding off-road, whether it's on a designated FSR or an unmarked trail, inherently carries risks. An accident could still result in damage to property (e.g., a fence, a cabin, or another rider's machine) or injury to another person. Without voluntary liability coverage, you would be personally responsible for these costs, which could quickly escalate into tens or even hundreds of thousands of dollars. This is why many experienced riders strongly advise securing private third-party liability coverage, even for purely recreational rides on general Crown land. [BC Liability Is Voluntary on Other Crown Land] highlights this important difference.
When Your Own Property is Involved (or Someone Else's Private Land)
The insurance landscape changes again when you're riding on private land. If you're on your own private property, or on private property with the owner's permission, the provincial ORV registration and insurance rules generally don't apply. Your machine doesn't have to be registered for use solely on private land. However, this doesn't mean you're off the hook for liability. If you're riding on your friend's ranch and accidentally damage their barn or injure another guest, your personal liability would likely fall under your homeowner's insurance, if it even covers such an incident, or you would be personally liable. If you regularly ride on private land that isn't your own, it's a good idea to discuss this with your private ORV insurer to ensure you have adequate coverage. They might offer specific endorsements for riding on non-owned private property. Furthermore, if you're outfitting your machine with protective gear like heavy-duty bumpers or rock sliders from SuperATV, you're already thinking about minimizing damage, but liability insurance is about protecting others from damage you might cause.
What "Liability Coverage" Actually Means on These Roads
When we talk about liability coverage, whether it's the mandatory $200,000 on FSRs or a higher limit you purchase privately, we're talking about protection if you are found legally responsible for causing harm to others. It's not about damage to your own machine or injuries to yourself. That's a different type of coverage entirely.
Property Damage to Third Parties
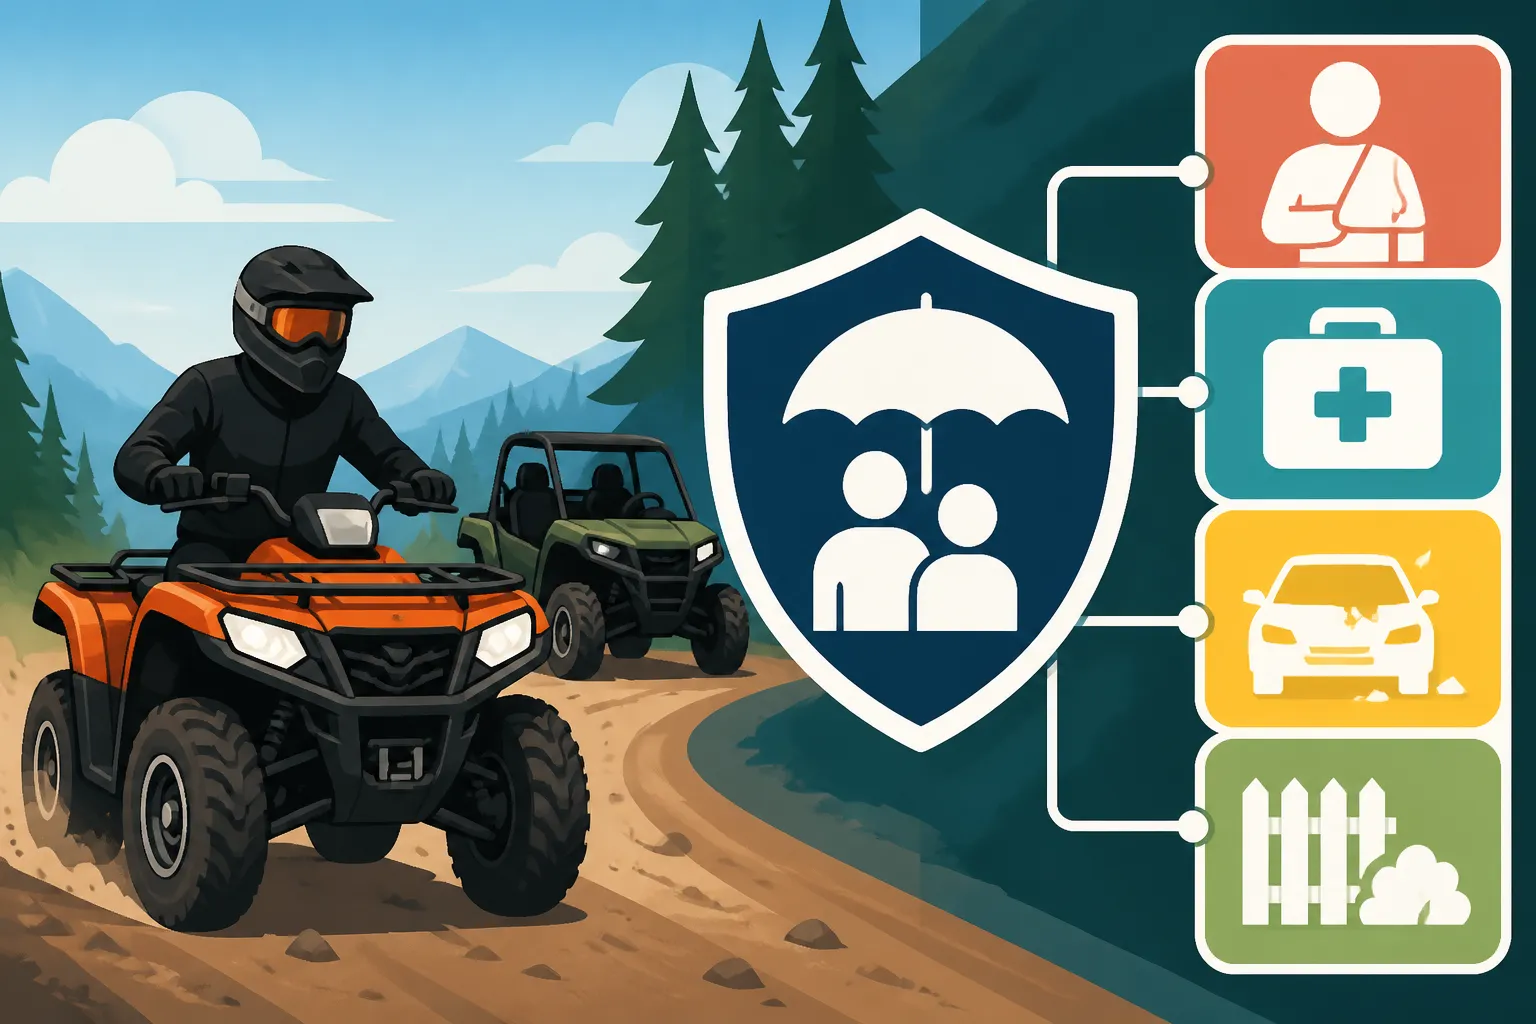
One of the primary functions of liability coverage is to pay for damage to other people's property. On a resource road, this could take many forms. Imagine you're riding around a blind corner and collide with a parked logging truck, damaging its fender. Or perhaps you lose control on a steep descent and veer off-trail, knocking over a gate or damaging a piece of surveying equipment left near the road. Even something as seemingly minor as your ATV's exhaust sparking a small brush fire (though this would also involve significant environmental penalties) could lead to substantial property damage claims. Your liability coverage would step in to cover the repair or replacement costs of that third-party property, up to your policy's limit. Without it, you'd be personally on the hook for those potentially very expensive repairs.
Bodily Injury to Third Parties
Perhaps even more critical, liability coverage pays for bodily injury that you inflict upon others. This is incredibly important when you consider the nature of ATV/UTV riding—it's fast, involves moving parts, and accidents can happen quickly and unexpectedly. If you collide with another rider or pedestrian on a resource road, and they suffer injuries, your liability insurance would cover their medical expenses, rehabilitation costs, lost wages, and even pain and suffering, up to your coverage limit. This also extends to passengers on your own machine. If a passenger on your side-by-side is injured in an accident where you are deemed at fault, your liability coverage would respond. Given the high cost of medical care and potential long-term impacts of serious injuries, having robust bodily injury liability coverage is paramount to protecting your financial future. This is a key reason why carrying [BC Insurance Proof on the Trail] is so important.
Exclusions and Limitations to Be Aware Of
It's vital to understand that liability coverage isn't a blank cheque. All policies come with exclusions and limitations. For instance, if you're riding under the influence of alcohol or drugs, operating your ORV recklessly (which could lead to [BC Fines for Careless Operation]), or participating in illegal activities, your insurance policy will likely be void, and you'll receive no coverage. Similarly, intentional acts of damage or injury are never covered. Your policy will also have a maximum limit—the $200,000 from ICBC for FSRs, or a higher amount if you purchased private coverage. If the total cost of damages and injuries exceeds this limit, you would be personally responsible for the difference. It's also important to ensure your vehicle is being operated according to its intended use and any conditions specified in your policy; for example, if you've added specialty parts from SuperATV, ensure they don't somehow void any factory warranties or policy stipulations related to modifications. Always read your policy documents carefully to understand what is and isn't covered.
Scenarios Where Liability Coverage Kicks In
Sometimes the best way to understand insurance is through real-world examples. Let's look at a few hypothetical situations where your liability coverage would become your financial saviour on a BC resource road.
Accidental Damage to Logging Equipment
Imagine you're navigating a narrow section of an FSR, perhaps admiring the rugged terrain, when you misjudge a turn. Your UTV scrapes against a piece of parked logging equipment—say, a feller buncher or a skidder—leaving a noticeable dent or even damaging some hydraulic lines. Industrial equipment like this is incredibly expensive to repair or replace, and any downtime for the company means lost revenue. In this scenario, your $200,000 mandatory liability coverage (if you were on an FSR) would be activated to cover the cost of repairs to the logging equipment. Without it, the logging company would come directly after you for damages, potentially involving legal action and leaving you with a massive bill that could easily climb into the tens of thousands of dollars.
Injury to Another Rider or Passenger
Consider a group ride on a popular trail that also serves as a resource road. You're riding with friends, and as you approach a muddy section, you accelerate to get through, losing control momentarily. Your ATV veers sideways, striking a fellow rider who was dismounted and checking a tire. They fall, breaking an arm and requiring significant medical attention and time off work. This is a classic liability claim. Your insurance would cover their medical expenses, rehabilitation, and potentially lost wages, as well as any legal costs if they decide to sue for damages. If your policy has higher limits from a private insurer, you'd have more protection, but even the mandatory $200,000 would begin to address the costs. This scenario underscores why [BC Accident Reporting on Crown Land] is a serious matter, as it will initiate the insurance claim process.
Hitting Wildlife or Parked Vehicles
Resource roads are wild places, and encounters with wildlife are common. While hitting a deer or elk might seem like an "act of nature," if your machine swerves and, in doing so, damages a parked vehicle or causes an injury to a bystander, your liability coverage could be triggered. For instance, if you swerve to avoid a bear and end up sideswiping a parked pickup truck belonging to a hunter, your liability coverage would pay for the damage to the truck. If your swerve also results in your passenger hitting their head and requiring medical attention, their injuries would also fall under your liability, assuming you were at fault for the incident. It's a chain reaction, and liability insurance is there to cover the damage you cause to others and their property.
Protecting Yourself Beyond the Minimum
While the mandatory $200,000 liability for FSRs is a start, it's really just that—a start. For true peace of mind and comprehensive protection, most riders look beyond the basic requirements, especially given the rising costs of repairs and medical care. This proactive approach is part of being a responsible rider in BC's backcountry. For those who frequently explore [BC Crown Land Riding Explained], voluntary insurance becomes an obvious choice.
Enhancing Your Coverage with Private Policies
As mentioned, private insurance companies offer specialized policies for off-road vehicles. These policies typically allow you to increase your third-party liability limits well beyond the $200,000 mandated for FSRs, often to $1 million, $2 million, or even more. This higher limit provides a much greater buffer against catastrophic claims. Beyond liability, private policies can offer collision coverage (to repair or replace your own machine if it's damaged in an accident, regardless of fault), comprehensive coverage (for theft, vandalism, fire, and other non-collision incidents), and even coverage for specific accessories you've added. If you've invested heavily in your machine, perhaps equipping it with robust suspension systems or utility boxes from SuperATV to handle BC's diverse terrain, protecting that investment with comprehensive and collision coverage is just good sense.
The Role of ATV Clubs and Their Benefits
Joining a local or provincial ATV club in British Columbia can offer numerous advantages, and insurance is often one of them. Many clubs work with private insurers to offer discounted rates on ORV insurance to their members. This is because clubs often promote safe riding practices, responsible land use, and provide training opportunities, which can reduce the risk profile of their members in the eyes of insurers. Beyond potential insurance discounts, clubs offer a wealth of local knowledge, organized rides, and advocacy for rider access to trails and resource roads. [What the Provincial Federation of ATV Clubs Does] includes working to secure such benefits for riders. These benefits can include workshops on safe riding techniques, advice on navigating specific resource roads, and updates on [BC Motor Vehicle Prohibitions Explained] in various areas.
Choosing the Right Coverage Amount for Peace of Mind
Deciding how much liability coverage you need is a personal choice, but it's one that deserves careful consideration. While $200,000 might seem like a lot, a serious accident involving multiple parties, significant property damage, or long-term injuries could easily exceed that amount. Many financial advisors recommend carrying at least $1 million in liability coverage for any vehicle, including ORVs, simply because the potential costs of a major accident can be astronomical. Think about your assets—your home, your savings, your future earnings. If a judgment against you exceeds your insurance coverage, those personal assets could be at risk. Investing a little extra in higher liability limits each year is a relatively small cost compared to the potential financial devastation of an underinsured accident.
Comparison of ORV Liability Coverage in BC
| Coverage Type | Applies To | Minimum Limit | Provider | Mandatory/Voluntary | What it Covers |
|---|---|---|---|---|---|
| Basic Third-Party Liability | Forest Service Roads (FSRs) | $200,000 | ICBC | Mandatory | Damage/injury caused to others on FSRs. |
| Third-Party Liability | Other Crown Land | Varies | Private | Voluntary | Damage/injury caused to others on general Crown land. |
| Third-Party Liability | Private Land | Varies | Private | Voluntary | Damage/injury caused to others on private property (may be covered by homeowner's). |
| Collision Coverage | All riding areas | Cost of repairs | Private | Voluntary | Damage to your own ORV in an accident. |
| Comprehensive Coverage | All riding areas | Replacement value | Private | Voluntary | Theft, fire, vandalism, etc. for your own ORV. |
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.