BC’s Three-Tier Insurance Rule
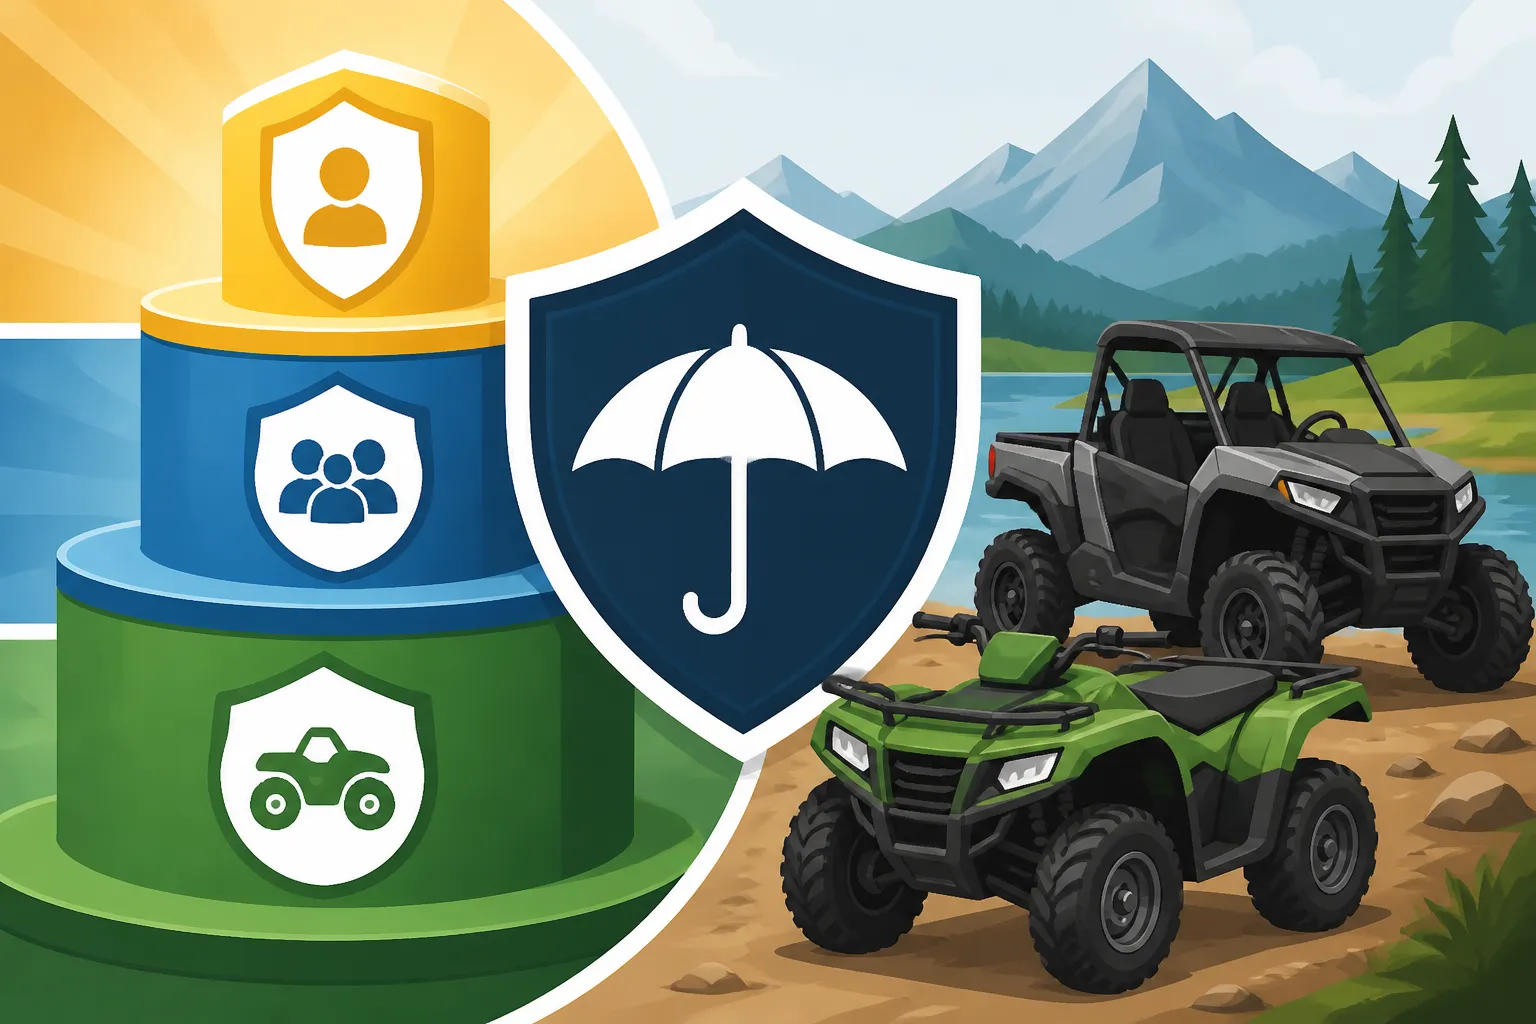
Navigating the world of ATV and UTV insurance in British Columbia can feel like deciphering ancient scrolls, leaving many riders scratching their heads and worrying about fines or worse. It’s not just about having a policy; it’s about having the right policy for where you plan to ride, and misunderstanding these distinctions can lead to serious headaches and financial strain. This guide will meticulously break down BC's unique three-tier insurance rule, helping you understand what coverage you need, when you need it, and why it's crucial for every off-road adventure.
Understanding BC's Unique Approach to ORV Insurance
British Columbia's off-road vehicle (ORV) insurance landscape is a bit different from what you might find for highway vehicles, and certainly distinct from many other jurisdictions. It’s not a simple one-size-fits-all situation, which often catches new riders or those new to the province off guard. The core idea is that the level of mandatory insurance changes dramatically depending on whether you're briefly touching a highway, riding on a resource road, or exploring vast stretches of Crown land. This nuanced system aims to balance access with accountability, ensuring that when incidents happen, there's a framework in place.
Why ORV Insurance Differs from Car Insurance in BC
When you insure your car or truck in BC, it's typically a comprehensive package through ICBC that covers you for most situations on public roads, with additional private options for extended coverage. For ORVs, the story takes a different turn. Highway vehicles operate under one set of rules, largely unified and universally understood for road use. ORVs, however, traverse a multitude of terrains – from designated trails to vast wilderness – each with its own specific risk profile and legal framework. This means that a single, all-encompassing mandatory insurance policy isn't practical or legally mandated for all scenarios. Instead, the province has carved out distinct tiers of coverage, reflecting the varied environments ORVs operate in. [BC's Certificate of Registration Explained] is a good read if you're still getting your head around the basic documentation for your machine.
The key distinction lies in the concept of "highway" versus "off-highway." Your quad or side-by-side isn't generally street-legal in BC, which immediately places it outside the standard highway insurance paradigm unless it's doing something very specific like crossing a road. This also means that liability, collision, and comprehensive coverage, which are often bundled for cars, become highly segmented and, in many cases, voluntary for ORVs. Riders often feel a sense of frustration because the rules seem unnecessarily complex compared to their daily driver, creating uncertainty about what they truly need before hitting the trails.
The Problem with "One Policy Covers All" Thinking
Many riders, especially those new to the sport or unfamiliar with BC's specific regulations, might assume that once they've registered their machine and perhaps bought some basic insurance, they're good to go everywhere. This couldn't be further from the truth in British Columbia. Relying on a single, blanket policy is a common trap that can lead to significant financial penalties or uncovered losses after an incident. Imagine you're out exploring a beautiful remote forest service road, enjoying the scenery, only to have a minor fender bender with another ORV or, worse, a logging truck. If you only have basic liability for crossing a highway, you'll quickly find yourself in a very difficult position.
This "one policy covers all" mentality often stems from a lack of clear, consolidated information, making it difficult for riders to understand the nuances. People often believe that if their machine is registered, it implies a certain level of insurance, but registration and insurance are distinct requirements. The registration process itself doesn't automatically trigger the right level of insurance for all riding conditions. [BC ORV Registration Cost] covers the initial fee you pay once, but don't confuse that with ongoing insurance. The crucial takeaway is that you need to actively assess your riding plans and adjust your insurance accordingly, rather than assuming a default level of protection.
Tier 1: Basic Autoplan for Highway Crossings
The first tier of BC's ORV insurance rule comes into play when your off-road vehicle interacts with public highways. While your quad or side-by-side isn't meant for sustained highway travel, there are specific, legally defined situations where you might need to briefly cross a highway to get from one section of trail to another. These are not opportunities for joyrides on paved roads, but rather specific, permitted maneuvers. For these fleeting moments, a very particular type of insurance is mandatory: a basic Autoplan policy.
When You Need Basic Autoplan on a Quad
You might be wondering, "Why would my off-road machine need 'Autoplan'?" It’s a valid question, as Autoplan is synonymous with highway vehicles in BC. However, the Off-Road Vehicle Act makes a specific exemption and requirement for ORVs that need to cross a highway. If you're riding a trail that gets bisected by a public road, and you need to legally cross that road – perhaps at a stop sign or a traffic light – you are temporarily operating within the jurisdiction of highway traffic laws. [BC Rules for Crossing a Highway] lays out the specifics of how to do this safely and legally.
In these instances, BC law mandates that your ORV must have at least basic Autoplan insurance. This coverage specifically addresses the liability risk associated with crossing a highway. Think of a common scenario: you're at the [Bear Creek OHV: BC's Largest Recreation Site], and you need to cross a short stretch of pavement to access a different section of the vast trail network. Without that basic Autoplan, you are not only breaking the law but also exposing yourself to potentially massive liability if you were to cause an accident with a highway vehicle or pedestrian during that brief crossing. It’s not about covering your machine for off-road damage, but about covering the risk to others when you briefly mix with highway traffic.
What Basic Autoplan Covers for ORV Highway Crossings
The basic Autoplan you purchase for highway crossings is strictly focused on third-party liability. This means it covers damage or injury you might cause to other people or their property while your ORV is on the highway, even if it's just for a few seconds during a crossing. It's not designed to cover damage to your own machine if you hit a car, nor does it cover your medical expenses if you get hurt. Its purpose is singular: to protect the public from the risks associated with an ORV briefly entering the highway environment.
For example, if you're crossing a road and accidentally clip the bumper of a passing car, this basic Autoplan would kick in to cover the repairs to that car. Without it, you'd be personally responsible for all damages, which could easily run into thousands of dollars. It’s a bare minimum requirement, designed to integrate ORV crossings into the existing highway insurance framework. [BC Requires Basic Autoplan on a Highway] highlights this requirement, underscoring that this tier of insurance is non-negotiable for these specific interactions with public roads. It's a small premium for a very specific, high-risk situation, often overlooked but critically important for legal and financial protection.
Tier 2: Forest Service Road and Resource Road Coverage
Moving beyond highway crossings, the next tier of insurance addresses riding on Forest Service Roads (FSRs) and other resource roads. These are the arteries of BC's vast backcountry, used by logging trucks, mining operations, and recreational users alike. Unlike a brief highway crossing, riding on an FSR often involves extended periods of travel on active industrial roads, which presents a unique set of risks. This is where the mandatory insurance requirements shift from basic Autoplan to a more robust liability coverage.
Mandatory Liability for Riding on an FSR
Forest Service Roads, and other roads built or maintained for industrial resource extraction, are not considered "highways" in the traditional sense, but they are also not simply "Crown land" for all purposes. They exist in a legal grey area where specific rules apply to ensure safety, especially given the heavy industrial traffic they often carry. Because these roads are open to the public but often host commercial vehicles, the province mandates a higher level of liability insurance for ORV riders. [BC Resource Roads Count as Crown Land] in some contexts, but their active use triggers distinct insurance requirements.
Specifically, if you're riding your ORV on a Forest Service Road, you are legally required to carry a minimum of $200,000 in third-party liability insurance. This isn't voluntary; it's a mandatory prerequisite for operating on these roads. The rationale is clear: the potential for serious accidents with large industrial vehicles is real, and the consequences can be catastrophic. Imagine encountering a loaded logging truck on a blind corner on an FSR near Squamish or Revelstoke. The damage and potential injuries from such an incident could far exceed basic Autoplan coverage, necessitating this higher minimum. This is an essential safety net, protecting both you and other road users from the significant financial fallout of a serious collision.
What $200,000 Liability Covers on a Resource Road
The $200,000 third-party liability coverage for FSRs is designed to cover damages or injuries you might cause to others or their property while operating your ORV on these roads. Just like with basic Autoplan, it does not cover damage to your own machine or your own medical expenses. Its primary function is to provide financial protection against claims made by third parties who are injured or whose property is damaged due to your negligence or involvement in an accident on an FSR. [What Liability Coverage Pays for on a Resource Road] is crucial for understanding the scope of this coverage.
Consider a scenario where you lose control on a gravel FSR, causing another recreational vehicle to swerve and hit a rock, or worse, impact a piece of logging equipment. Without this $200,000 liability coverage, you would be personally on the hook for all repairs to the other vehicle, any medical expenses of its occupants, and any damage to industrial property. This amount is seen as a reasonable minimum to cover the potential costs of accidents involving vehicles that can often be much larger and heavier than a typical ORV. This insurance provides a critical buffer against financial ruin in the event of a significant incident in the BC backcountry. Many riders might consider adding components like a SuperATV winch or heavy-duty bumpers to their machines, enhancing their machine's capability and protection, which could indirectly mitigate some minor damage scenarios, but robust liability coverage remains paramount for safeguarding against third-party claims.
Tier 3: Voluntary Coverage for Crown Land and Private Property
Beyond highway crossings and Forest Service Roads, the vast majority of ORV riding in British Columbia occurs on general Crown land or, less commonly, private property. In these expansive and often remote areas, the mandatory insurance rules loosen considerably. However, "voluntary" does not mean "unnecessary." This third tier is about making informed choices to protect yourself, your machine, and your finances, even when the law doesn't explicitly demand it.
Voluntary Coverage for General Crown Land Riding
For the vast majority of off-road riding on general Crown land – those wide-open spaces, intricate trail networks, and remote wilderness areas that make BC such an ORV paradise – there is no mandatory third-party liability insurance requirement under the Off-Road Vehicle Act. This often comes as a surprise to riders, who might assume that some level of government-mandated coverage is universal. [BC Crown Land Triggers the Registration Rule], but not necessarily a specific insurance type.
However, just because it's not mandatory doesn't mean it's not a smart idea. Imagine you're riding on an unmarked trail in the Cariboo, enjoying the solitude, and accidentally collide with another rider, or perhaps cause damage to a remote cabin that turns out to be on leased Crown land. Without any liability coverage, you would be personally responsible for all resulting damages and injuries. This is where personal risk assessment comes in. Many riders choose to extend their $200,000 FSR liability coverage to cover all Crown land riding, or they opt for higher limits through private insurers. It's about weighing the peace of mind against the potential, albeit often rare, risks of an incident in a less regulated environment.
Optional Collision, Comprehensive, and Increased Liability
This tier is where you have the most flexibility to tailor your insurance to your specific needs, machine, and riding habits. While liability might be voluntary on general Crown land, collision and comprehensive coverage are almost always optional extras for ORVs, regardless of where you ride. These are the coverages that protect your machine from damage or loss.
- Collision Coverage: This pays for damage to your own ORV if you're involved in a collision, whether it's with another vehicle, an object (like a tree or rock), or if you roll your machine. If you've invested in a brand-new side-by-side or spent a lot on SuperATV upgrades like portals or a long-travel kit, this coverage is absolutely vital.
- Comprehensive Coverage: This protects your ORV from non-collision-related damage or loss, such as theft, vandalism, fire, or natural disasters. Given how frequently ORVs are targets for theft, and the remote locations they are often parked, comprehensive coverage can be a wise investment.
- Increased Liability: Even if $200,000 is the mandatory minimum for FSRs, many experienced riders choose to carry higher limits, such as $1 million or $2 million. The cost of a serious injury or fatality can easily exceed $200,000, leaving you exposed. This is particularly relevant if you frequently ride in groups, or in areas with potential interactions with other people or property. [BC Insurance Price Gaps Riders Talk About] often center on finding affordable, robust private options. [Buying Private Coverage for Resource Road Riding] offers more detail on how to source this.
Riding on private property, such as your own land or with permission on a friend's acreage, typically doesn't trigger any mandatory ORV insurance requirements. However, your homeowner's insurance might have specific clauses regarding motorized vehicles, or you might want to ensure you have personal liability in case a guest is injured while riding your machine. Always check with your insurance provider about what is covered under your existing policies before assuming you're protected.
How to Get Your ORV Insured in British Columbia
So, you've understood the three tiers, and now you're ready to get the right coverage. But how exactly do you go about it in BC? It's not always as straightforward as walking into any insurance office. Because ORV insurance can be a bit specialized, knowing where to go and what to ask for is key.
Autoplan Brokers Handle ORV Insurance Needs
When it comes to getting that mandatory basic Autoplan for highway crossings, or even the $200,000 liability for Forest Service Roads, your go-to resource is an Autoplan broker. These are the same brokers who handle your car insurance with ICBC. While ICBC is the sole provider of basic Autoplan, they also facilitate access to the mandatory FSR liability. [BC Autoplan Brokers Handle ORV Registration] and they also manage the associated insurance.
It's crucial to find a broker who is knowledgeable about ORV regulations, as not every agent will be intimately familiar with the nuances of the Off-Road Vehicle Act and its insurance requirements. Don't be afraid to ask questions, and make sure they understand where you intend to ride. A good broker will walk you through the options, ensuring you get the specific liability coverage you need for FSRs, and perhaps even discuss private options for comprehensive or extended liability. Remember, [Nine Hundred Brokers Province-Wide] means there are options, so seek out one with specific ORV expertise if you have complex needs.
Private Insurers for Expanded Coverage
While ICBC handles the mandatory basic Autoplan and the minimum FSR liability, they don't offer the full spectrum of optional ORV coverage. For things like collision, comprehensive, or higher limits of liability (e.g., $1 million or $2 million for Crown land riding), you'll need to turn to private insurance providers. These companies specialize in recreational vehicle insurance and can offer policies tailored to your specific machine and riding style.
Many private insurers offer packages that bundle collision, comprehensive, and enhanced liability coverage. This is often where you can truly protect your investment, especially if you have a high-value machine or have added significant aftermarket parts from companies like SuperATV. When shopping around, compare quotes from several providers. Ask about deductibles, coverage limits, and any exclusions (e.g., racing, rental use). It's also worth asking if your existing home or auto insurer offers a discount for bundling your ORV policy with them. This is where you can explore options like a [BC ATV Insurance Cost Per Year] and weigh it against the potential risks.
What to Bring to Your Broker or Insurer
To make the insurance process as smooth as possible, gather all necessary documentation before you visit your broker or start an online application. Being prepared can save you a lot of back-and-forth.
Here’s a general checklist of what you'll typically need:
- Your ORV's Certificate of Registration: This is your proof of ownership and shows the VIN. If you're new to BC, or have just acquired your machine, ensure you've already completed the registration process. [BC Transfer of Ownership Explained] might be relevant if you've recently bought your machine.
- Your Driver's Licence: Essential for identification and insurance purposes.
- Proof of Address: A utility bill or other official document showing your current BC address.
- ORV Make, Model, and Year: Specific details about your machine.
- Vehicle Identification Number (VIN): This unique serial number is critical for identifying your ORV.
- Details of Any Modifications or Upgrades: If you've added significant accessories or performance parts, especially from brands like SuperATV, your insurer will want to know about them, as this can affect the insured value and sometimes the premium.
- Your Riding Habits: Be prepared to discuss how often you ride, where you typically ride (FSRs, Crown land, specific recreation sites), and if you ever participate in organized events.
- Claims History: Information about any previous insurance claims for any vehicle you've owned.
Having these details handy will ensure your broker or insurer can provide accurate quotes and the appropriate coverage for your specific needs, helping you avoid frustrating delays.
Common ORV Insurance Scenarios and Questions
Despite the rules, real-life riding situations often bring up unique questions and scenarios. It's helpful to anticipate these and understand how BC's three-tier system might apply. Being prepared means you can focus on the ride, not the potential legal headaches.
Riding with Two Owners: Who Insures What?
It's increasingly common for ORVs, especially expensive side-by-sides, to be jointly owned by two or more individuals, perhaps family members or close riding buddies. This shared ownership can sometimes create confusion around insurance. When a machine has multiple owners listed on the [BC Transfer of Ownership Explained] document and the Certificate of Registration, typically, one primary owner will be designated for insurance purposes.
However, the policy should ideally reflect the interests of all owners. For liability coverage, the policy usually protects any authorized operator, but it's crucial to confirm this with your broker. For collision and comprehensive, ensure that all owners have an insurable interest in the machine. In a shared ownership situation, all parties should clearly understand who is responsible for paying premiums, what coverages are in place, and what happens in the event of a claim. It’s a discussion worth having before hitting the trails to avoid any future disputes or uncovered losses.
What About ORV Rental Fleets?
If you're considering starting an ORV rental business, or if you're thinking about renting a machine for a guided tour, the insurance landscape shifts again. Rental fleets operate under commercial insurance policies, which are significantly different and more comprehensive than individual recreational policies. [BC ATV Rentals: What They Cost] will typically include the necessary insurance, but it's important to understand what that entails.
When you rent an ORV from a company, that company is responsible for ensuring the machine is properly registered and insured. Their commercial policy will cover the machine itself, and typically include robust third-party liability coverage for the renter, subject to the terms of the rental agreement. As a renter, you will likely be required to sign a waiver that outlines your responsibilities and any deductibles you might be liable for in case of damage to the machine. Always read the rental agreement carefully, and ask about the specifics of their insurance coverage, including any optional damage waivers they might offer. You won't be personally purchasing Autoplan for a rental, as that falls to the commercial operator.
Accidents on Crown Land: Who Pays?
This is where the distinction between mandatory and voluntary insurance becomes critically important. If you have an accident on general Crown land – an area not classified as a highway or an FSR – and you only have the mandatory basic Autoplan for highway crossings, or just the $200,000 FSR liability without extending it to other Crown land, you could find yourself in a very precarious position. [BC Liability Is Voluntary on Other Crown Land] means if you crash into another rider, or cause damage to someone else's property, you are personally responsible for all costs.
Without specific liability coverage for general Crown land, there's no insurance policy to step in and cover those third-party damages or injuries. This can mean personal assets are at risk. This is precisely why many experienced riders opt for higher liability limits through private insurers, ensuring they are protected no matter where they ride. While the chance of a serious incident with a third party on remote Crown land might seem low, the financial consequences if it does happen can be devastating. This is why investing in comprehensive liability, collision, and comprehensive coverage through a private insurer for all your riding areas is a strong recommendation for anyone who values peace of mind and financial security.
The Cost of ORV Insurance in BC
Let's be real, nobody enjoys paying for insurance, but it's a necessary part of responsible ORV ownership. The cost of ORV insurance in BC can vary significantly based on a multitude of factors. Understanding what influences these costs can help you budget and make informed decisions about your coverage.
Factors Influencing Your Insurance Premium
Just like with car insurance, several elements come into play when calculating your ORV insurance premium. It’s not a flat fee, and what one person pays might be very different from another.
Key factors include:
- Type of Machine: Is it an ATV, a side-by-side, a dirt bike, or a snowmobile? More powerful, expensive, or high-performance machines typically cost more to insure, especially for collision and comprehensive. A brand-new SuperATV equipped UTV will likely have a higher premium than a vintage quad.
- Your Riding Habits: Do you ride year-round, or only seasonally? Do you stick to local trails, or venture into remote areas and FSRs frequently? More extensive or higher-risk riding typically leads to higher premiums for voluntary coverage.
- Your Driving/Riding Record: A clean record with no at-fault accidents or traffic violations (even on highways with your car) can lead to lower premiums.
- Coverage Limits and Deductibles: Opting for higher liability limits (e.g., $2 million instead of $200,000) will increase your premium. Similarly, choosing a lower deductible for collision or comprehensive coverage will mean a higher premium, but you'll pay less out-of-pocket if you make a claim.
- Location: While not as prominent as with car insurance, your primary residence location can sometimes play a minor role.
- Discounts: Ask your broker or private insurer about available discounts. These might include multi-vehicle discounts, bundling discounts (if you have other insurance with the same provider), or discounts for being a member of an authorized ATV or ORV club in BC. [BC Club Memberships and What They Buy] can sometimes include insurance benefits.
- Age and Experience: Experienced adult riders generally receive better rates than younger, less experienced operators, especially when considering voluntary coverage.
Comparing ICBC and Private Insurer Costs
For the mandatory basic Autoplan for highway crossings, and the $200,000 liability for FSRs, ICBC is your only option. The costs for these are set by the provincial insurer and are generally consistent across all brokers. These mandatory coverages represent the baseline.
When you move into voluntary collision, comprehensive, and extended liability for Crown land, that's where private insurers come into play, and pricing can vary significantly. It's highly recommended to get quotes from multiple private providers. You'll likely find differences in premiums, deductible options, and the specific terms and conditions of their policies. Some private insurers might offer specialized packages for ORVs that better suit your needs than a generic recreational vehicle policy. [BC Insurance Price Gaps Riders Talk About] often arise from the variations between these private offerings.
Don't just look at the bottom line premium; also compare the coverage details, exclusions, and the reputation of the insurer for handling claims. A slightly higher premium might be worth it for better coverage or a more reliable claims process.
What Happens When You Sell Your Insured Machine?
When it comes time to sell your ORV, what happens to your insurance? Just like with a car, your ORV insurance policy is tied to you and your machine. When you sell the machine, you need to contact your broker or insurer to cancel the policy.
If you've paid premiums in advance, you'll typically receive a refund for the unused portion of your policy. It's important to do this promptly after the sale to avoid paying for coverage you no longer need. The new owner will then be responsible for obtaining their own registration and insurance for the machine. The registration itself, while it [BC Registration Lasts as Long as You Own It], becomes void upon sale, and the new owner must re-register the machine in their name. This ensures that the insurance liability shifts cleanly from you to the new owner, preventing any confusion or lingering responsibility.
| Insurance Tier | Required For | Coverage Type | Covered On | Provided By |
|---|---|---|---|---|
| Tier 1: Basic Autoplan | Highway Crossings | Third-Party Liability (Mandatory) | Public Highways (brief crossings only) | ICBC (via broker) |
| Tier 2: FSR Liability | Forest Service Roads & Resource Roads | $200,000 Third-Party Liability (Mandatory) | Designated FSRs/Resource Roads | ICBC (via broker) |
| Tier 3: Voluntary Coverage | General Crown Land, Private Property, All Areas | Collision, Comprehensive, Higher Liability | All riding areas | Private Insurers |
Penalties for Non-Compliance
Ignoring BC's ORV insurance rules isn't just a matter of tempting fate; it can lead to tangible and costly penalties. Law enforcement officers, including RCMP and Conservation Officers, have the authority to enforce the Off-Road Vehicle Act and its associated regulations, which include insurance requirements.
Fines for Uninsured ORV Operation
Operating an ORV without the mandatory insurance for a given area can result in significant fines. If you're caught crossing a highway without basic Autoplan, or riding on an FSR without the mandatory $200,000 liability, you could face a violation ticket. These tickets are not merely a slap on the wrist; they come with substantial financial penalties that can quickly ruin a day of riding. [BC Penalties for Riding Unregistered] are often discussed, but remember that insurance non-compliance carries its own distinct set of penalties.
Beyond the immediate fine, being caught without the proper insurance means you are personally exposed to immense financial risk. If you cause an accident while uninsured, you will be solely responsible for all damages and injuries. This could lead to lawsuits, asset seizure, and long-term financial hardship. It's a risk simply not worth taking, especially when the cost of the required liability coverage is relatively minor compared to the potential consequences.
Legal and Financial Consequences of an Accident While Uninsured
The financial impact of an accident while uninsured is perhaps the most daunting consequence. Imagine an unfortunate scenario: you're riding your ORV on a Forest Service Road, without the mandatory $200,000 liability coverage, and you collide with another vehicle. The other driver is injured, and their vehicle is severely damaged.
In this situation, you would be personally liable for:
- Medical Expenses: The costs of the other driver's injuries, including ambulance, hospital stays, rehabilitation, and long-term care. These can easily reach hundreds of thousands of dollars.
- Lost Wages: Compensation for any income the injured party loses due to their injuries.
- Vehicle Damage: The full cost of repairing or replacing the other vehicle.
- Legal Fees: The costs associated with defending yourself against a lawsuit, which could be substantial even if you win, and far greater if you lose.
This isn't just theoretical; these scenarios play out in real life. Without insurance, your personal savings, home, and other assets could be at risk. The legal process can be lengthy, stressful, and incredibly expensive. The minimal cost of obtaining the proper liability coverage pales in comparison to the potential financial devastation of an uninsured accident. This is why understanding and adhering to [BC ATV Insurance Requirements] is not just about following the law, but fundamentally about protecting your financial future.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.